The Agentic Post
Breaking
Gemini’s Multimodal Features, Explained  Â·  ChatGPT Custom GPTs, Explained  Â·  What Is Constitutional AI? Explained  Â·  AI Capex Explained for Investors  Â·  AI Startup Valuations: How They Are Set  Â·  How to Reskill for an AI Job Market  ·  
Home/Business/Markets
Why AI Stocks Swing So Hard on Earnings

Why AI Stocks Swing So Hard on Earnings

Markets

An explainer on why AI-linked stocks move so dramatically on earnings reports, covering capex guidance, trade repricing, and sector-specific divergence.

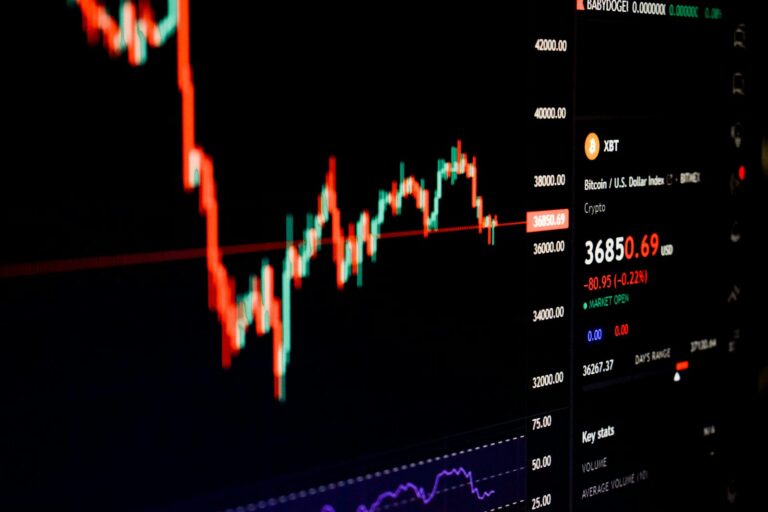
This is informational, not financial advice. AI-linked stocks have developed a habit of moving dramatically on earnings day, sometimes in the opposite direction the headline numbers suggest.

Strong revenue can still trigger a selloff. Our coverage of a major chip stock selloff is the clearest example: 36% year-over-year revenue growth, and the stock still dropped, because the accompanying capex guidance spooked investors about margin compression. Revenue growth paired with spending that outpaces it can read as a warning, not good news.

Much of the volatility reflects a broader repricing of an AI trade that ran up sharply over recent quarters, not purely a reaction to one report. A stock that’s climbed steeply is simply more exposed to a sharp pullback on anything that reads as mildly disappointing.

Different parts of the AI trade move independently. Our coverage of a single earnings week found nearly $1.5 trillion in combined market value shifting across three companies, with infrastructure providers rewarded while a consumer-facing AI company was punished the same day.

Capex-to-revenue trajectory, segment-specific growth, and balance sheet strength relative to peers matter more than headline revenue and profit. See investor.gov for general investing education.
Up Next
How Much Funding Do AI Startups Need?

How Much Funding Do AI Startups Need?

Funding & Startups

A practical guide to sizing an AI startup fundraise, covering realistic benchmarks, compute cost modeling, and the role of venture debt.

“How much should I raise” doesn’t have a universal answer, but the current funding environment has shifted what a reasonable number actually looks like.

Our look at H1 2026 venture data found two frontier labs absorbing roughly 43% of all global startup funding combined. Most founders raising a seed or Series A are operating in a genuinely tighter environment than the aggregate numbers suggest.

Size the raise to your actual compute costs. Unlike traditional software, many AI companies carry real, ongoing model API or infrastructure costs that scale with usage from day one. Underestimating this is a common way runway calculations go wrong specifically for AI products.

Venture debt has become a meaningful supplement to equity rounds for AI startups with predictable, growing infrastructure costs, extending runway without the dilution of raising early at a depressed valuation.

Our founder’s primer on AI fundraising covers what investors are actually asking now: what stops a well-resourced competitor from replicating this, and do unit economics hold up if model costs keep dropping. Size your raise around convincing answers to both.

Track funding activity directly at Crunchbase.